
Many companies with sufficient assets to offer as collateral still end up putting their owners’ personal assets at risk through personal guarantees, simply because this is the first option presented by the bank during negotiations. Pedro Daniel Magalhães, an executive with experience in structured credit and financial management, believes that although this choice may seem simpler, it is not always the option that best protects the company and its founders.
Before signing any credit agreement, it is worth identifying which forms of collateral the business itself already has available. In many cases, business owners may not realize that these assets could replace a personal guarantee during negotiations.
Why Are Personal Guarantees So Commonly Required Even Though They Are Not the Only Option?
A personal guarantee makes things easier for the bank. Instead of evaluating and formalizing a specific form of collateral, the lender obtains a direct commitment from the owners to repay the debt with their personal assets, reducing the amount of analysis and documentation required by the financial institution.
For the borrower, however, this simplicity comes at a high cost: it turns a corporate debt into a personal obligation, exposing assets that, in principle, should be protected by the company’s legal structure. In practice, a personal guarantee can undermine the very protection designed to separate the risks of the business from the personal financial risks of its owners.
What Collateral Can a Company Offer Without Putting Its Owners’ Personal Assets at Risk?
Equipment, company-owned real estate, inventory, and even future receivables can be used as collateral through mechanisms such as security interests or pledges, without requiring the owners to put their personal assets on the line.
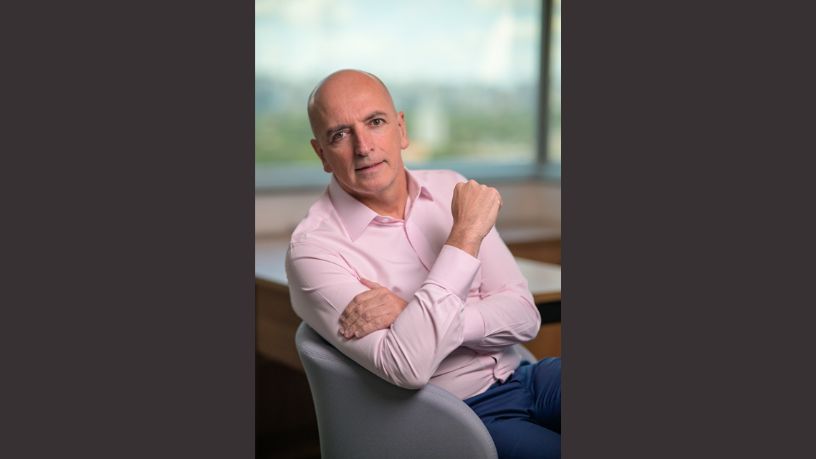
Companies with significant operating assets, Pedro Magalhães points out, often fail to present these alternatives to the bank, accepting personal guarantees either because they are unaware of the available options or because they are in a hurry to close the deal. Taking inventory of these assets before negotiations begin can already change the course of the conversation with the lender.
Why Does the Cost of Credit Change Depending on the Type of Collateral Offered?
Well-structured collateral with a clear market value and reasonable liquidity tends to reduce the lender’s perceived risk in much the same way as a personal guarantee, since both provide a secondary source of recovery in the event of default.
The key difference lies in who bears the risk. When company assets are pledged as collateral, the owners’ personal assets remain protected, and the exposure is limited to assets already held by the business. In the event of financial difficulties, the bank may enforce its rights against the pledged asset, but the owners’ homes, cars, or personal savings are not part of the equation.
When Is a Personal Guarantee Truly Unavoidable?
Early-stage companies without significant assets formally held by the legal entity often have little choice but to provide personal guarantees, since they have not yet accumulated enough operating assets to offer as collateral. In this scenario, a personal guarantee can serve as a temporary bridge until the company builds its own asset base and is able to renegotiate these terms in future credit agreements.
In these cases, Pedro Daniel Magalhães recommends negotiating clear limits on the personal guarantee, such as a maximum guaranteed amount or a defined term, rather than accepting an unrestricted commitment that could remain in effect longer than necessary to secure the financing.
What Does This Choice Mean for the Owners’ Personal Assets?
The decision about which type of collateral to offer rarely receives as much attention as the interest rate during negotiations, yet its impact can be far more lasting. A high interest rate affects the company’s financial performance, while a poorly negotiated personal guarantee can put the personal assets of those who run the business at risk.
According to Pedro Daniel Magalhães, identifying the available business assets that could be offered as collateral before accepting any credit proposal is a simple step that many companies overlook, precisely because they treat it as a bureaucratic detail rather than a strategic decision about asset protection.